
Common Money Myths That Keep People Stuck Living Paycheck to Paycheck
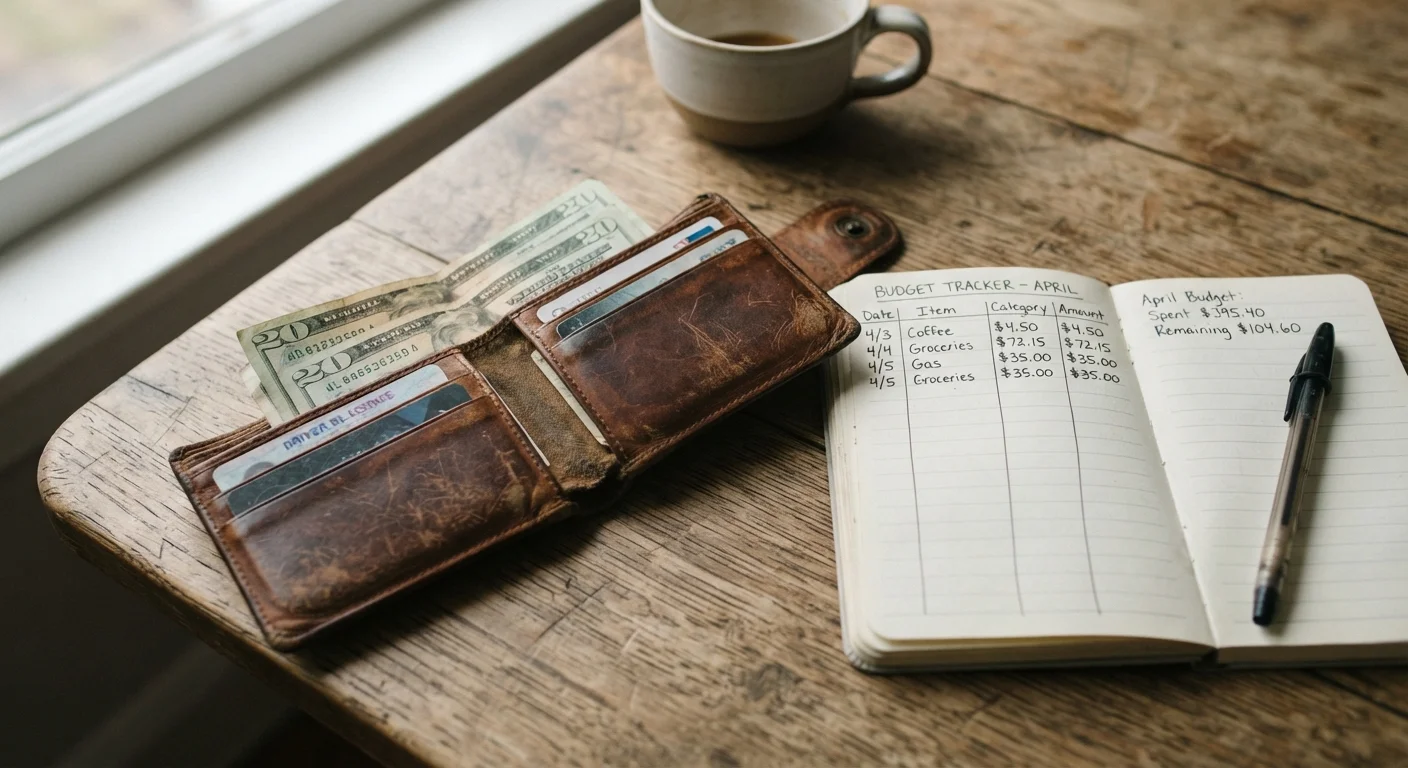
Photo: findbestways.com editorial
Key Takeaways
- Earning more income does not automatically fix a paycheck-to-paycheck cycle if spending habits stay the same.
- A small emergency fund reduces the need to rely on high-interest debt when unexpected costs hit.
- Credit cards are not inherently harmful; carrying a balance at high interest is what causes damage.
- Budgeting does not require tracking every dollar to be effective.
- Waiting until debt is fully paid off before saving often delays financial stability longer than necessary.
Why money myths stick around
Financial advice travels fast and loses accuracy along the way. A tip that worked in one person's situation gets repeated as a universal rule, and before long it sounds like settled wisdom. For budget-conscious adults trying to stop the paycheck-to-paycheck cycle, acting on bad information costs real money and real time.
The myths below are common, widely repeated, and worth examining closely. Some contain a grain of truth stretched too far. Others are flat wrong. In each case, understanding the actual mechanics helps you make decisions based on how money works, not how people assume it works.
Similar pattern-matching problems show up in other areas of household spending. The deck maintenance myths that cost homeowners money article shows how misplaced confidence in common knowledge leads to unnecessary costs around the home.
Myth
You just need to earn more money to stop living paycheck to paycheck.
Fact
Income level alone does not determine financial stability. Spending patterns, debt obligations, and savings habits matter at every income level.
People across a wide range of incomes report living paycheck to paycheck. When spending expands to match each raise, higher earnings produce the same outcome. This pattern, sometimes called lifestyle inflation, means a salary increase gets absorbed by upgraded expenses rather than building a cushion. Addressing the gap between income and outflow requires examining both sides of that equation, not just one.
Myth
You need to be debt-free before you start saving.
Fact
Carrying a small savings buffer while paying down debt reduces the likelihood of going deeper into debt when an unexpected expense hits.
Without any savings, a car repair or medical copay often goes on a credit card, adding to the debt you are trying to eliminate. A modest emergency fund, even a few hundred dollars in a basic savings account, breaks that cycle. Many nonprofit financial educators recommend building a small buffer first, then directing extra funds toward high-interest debt, rather than waiting until all debt is cleared before saving anything.
Myth
Credit cards are the reason people stay broke.
Fact
Credit cards are a financial tool. Carrying a balance at high interest is costly, but paying the full balance monthly costs nothing in interest and can help build credit history.
The problem is not the card itself; it is borrowing money at 20-plus percent interest to fund spending that exceeds your income. For someone who pays the statement balance in full each month, a credit card functions as a short-term float with no interest charge. Avoiding credit cards entirely can also leave people without a credit history, which affects mortgage rates, rental applications, and sometimes employment screening.
Myth
Budgeting means tracking every single dollar you spend.
Fact
A budget only needs to account for the spending categories that move your financial situation. Precision on small purchases is optional, not required.
Obsessive tracking is one reason people abandon budgets quickly. A simpler approach works for many households: identify fixed monthly obligations, estimate variable spending in a few broad categories, and confirm the total stays below take-home pay. Automated transfers to savings at the start of each pay period can do more than detailed expense logs because they act before discretionary spending happens rather than recording it after.
Myth
Renting is just throwing money away.
Fact
Renting provides housing in exchange for payment. Whether buying builds more wealth depends on local market conditions, how long you stay, and the full cost of ownership.
Homeownership can build equity over time, but it also carries costs renters do not pay: property taxes, homeowners insurance, maintenance, and mortgage interest. In high-cost markets or when someone plans to move within a few years, renting can be the financially sound choice. Framing rent as wasted money pressures people into purchases they cannot afford, which tends to produce financial stress rather than stability.
Myth
Small daily purchases like coffee or lunch are why most people cannot get ahead.
Fact
Cutting small discretionary purchases rarely produces the savings needed to change a household's financial trajectory. Large fixed costs carry far more weight.
The math on daily coffee, for example, comes to a few hundred dollars a year at most. That is real money, but small relative to housing, transportation, or high-interest debt. Focusing on minor purchases can distract from decisions that carry ten or twenty times the financial weight. Addressing a high-rate auto loan, renegotiating an insurance premium, or refinancing at a lower mortgage rate can save thousands annually.
What actually moves the needle
Correcting these myths does not guarantee financial improvement on its own. What it does is clear the path so that practical steps, consistent habits, and realistic goals have room to work. Misinformation tends to produce either paralysis (waiting until you earn more, waiting until debt is gone) or misdirected effort (tracking every coffee while ignoring large recurring expenses).
Focus on the decisions that carry the most weight: housing costs, transportation, recurring subscriptions, and high-interest debt. Those four categories typically account for the majority of a household budget. Getting them under control matters more than optimizing the margins.
Accurate information about routine expenses matters in other areas too. If you drive, the car fluid myths that lead to expensive mistakes are worth reviewing, since overspending or under-maintaining a vehicle shows up quickly in a tight budget.
This article is for general informational purposes only and does not constitute financial advice. Consider consulting a certified financial planner or nonprofit credit counselor for guidance specific to your situation.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.